- umkm
- e-commerce
- engineering
Marketplace PPh 22 Withholding 0.5%: Guide for SMEs 2026
Understand the marketplace PPh 22 withholding of 0.5% live since October 2026: the Rp500M turnover statement, margin impact, slip reconciliation, and SPT data.
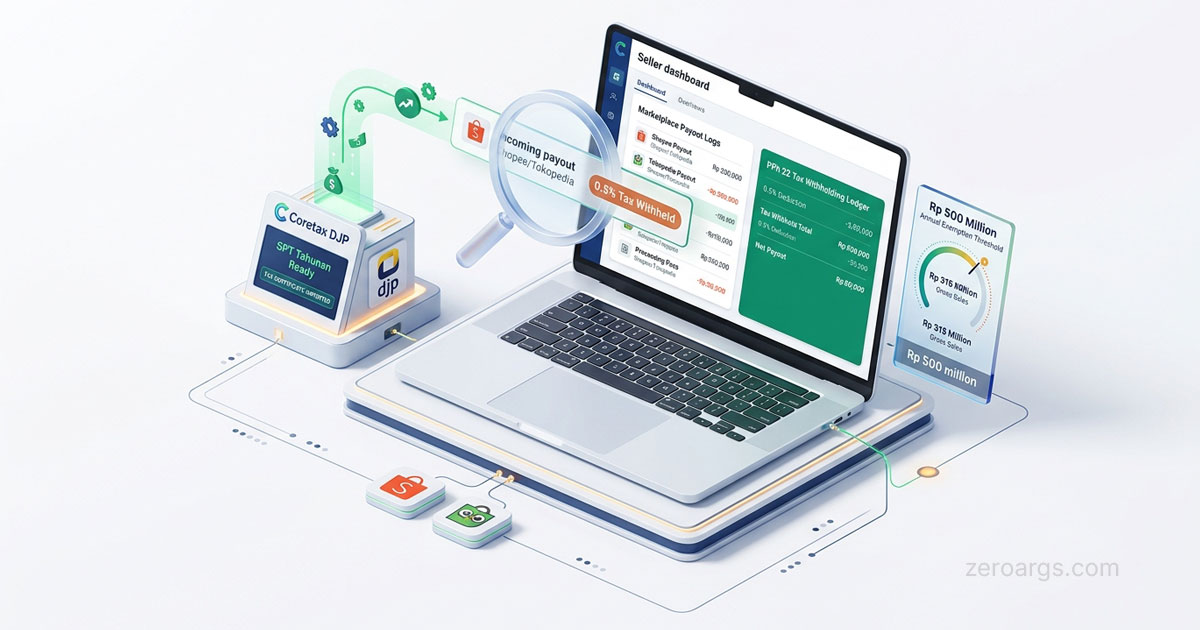
Check your marketplace payout in October 2026 and it looks slightly off from last month? Not a bug in your bank reconciliation. Since October 1, 2026, four e-commerce platforms appointed by Indonesia's Directorate General of Taxes (DJP) have been executing the marketplace PPh 22 withholding at 0.5% of every seller's gross turnover — and most Indonesian SMEs found out not from a press release, but from a small gap in their settlement statement. This article skips the news recap and covers the layer the media ignores: how to structure your sales data so the 0.5% cut is traceable per channel, the Rp500 million exemption threshold is monitored automatically, and the withholding slips land cleanly in your annual Coretax return.
1. What the Marketplace PPh 22 Withholding Actually Is
The legal basis is PMK 37/2025, implemented from October 1, 2026 under DJP press release SP-23/2026 and the Tax Director General's appointment decision of September 24, 2026. The four appointed withholding entities are PT Shopee International Indonesia (Shopee), PT Tokopedia (Tokopedia), PT Global Digital Niaga Tbk (Blibli), and PT Ecart Webportal Indonesia (Lazada). The list can grow through future appointment decisions, so don't assume other platforms are permanently off the hook.
The mechanism is simple but often misunderstood:
- The rate is 0.5% of gross turnover received by the seller, excluding VAT (PPN) and luxury goods sales tax. Gross turnover is counted after adjustments for the seller's own marketing costs.
- Withholding happens when the marketplace receives the payment, not when the order is placed.
- This is not a new tax. The amount withheld counts as a tax credit within the running year or as part of your final income tax settlement.
DJP's own example: if monthly gross turnover on one marketplace is Rp1,000,000, the withheld PPh is Rp5,000. Tiny per transaction — but at Rp50 million per month it becomes Rp250,000 per month per platform, which a small business can feel if it goes unplanned.
2. Who Pays and Who Is Exempt: The Rp500 Million Turnover Statement
The relief applies to individual taxpayers (wajib pajak orang pribadi). If your business's cumulative gross turnover in the running tax year stays at or under Rp500 million, marketplaces will not withhold PPh 22 — provided you submit a statement letter in the format attached to PMK 37/2025, signed over an IDR 10,000 duty stamp, and uploaded through each platform's designated mechanism.
Three rules get missed most often:
- One NPWP/NIK, one statement. Your statement covers every account on every marketplace at once — you don't need a copy per platform.
- Turnover accumulates across marketplaces. Rp300 million on Shopee plus Rp250 million on Tokopedia means you have passed the threshold, even though each platform individually is under Rp500 million.
- Threshold crossed mid-year? Submit a statement marked "exceeding Rp500 million" no later than the end of the month the threshold is passed. Withholding starts the following month. In DJP's example: the threshold is crossed in March, so April onward is withheld at 0.5%.
Businesses structured as corporate entities (badan usaha) get no such statement facility and are withheld per the regulation. Sellers holding an SKB — Indonesia's exemption certificate for withholding — must submit that instead. Note also that PPh 22 is separate from VAT: if you are a VAT-registered merchant (PKP), your e-invoicing obligations continue as usual.
3. Margin Impact: Marketplace vs Your Own Website
The 0.5% withholding changes your unit economics. It is not a platform fee (so it does not benefit from the government-mandated 50% service-fee discount for micro and small sellers), and it is not optional. Compare the two channels:
| Aspect | Marketplace sales | Own-website sales |
|---|---|---|
| Who withholds PPh 22 | Appointed marketplaces | No third party; you do it yourself |
| Settlement timing | Deducted at payout | You pay monthly yourself (Coretax billing) |
| Rp500M statement facility | Applies (individuals) | Not relevant — nothing is withheld |
| Monthly withholding slip | Yes, from each marketplace | None; use your own payment receipts |
| Effect on margin | Payout reduced by 0.5% on top of admin/commission fees | Same tax cost, but nothing clipped off payouts |
The key insight: the effective tax burden is equal (0.5% of turnover under the final income tax scheme) — what differs is cash timing and administration. On your own website, that 0.5% stays in your account until the monthly payment deadline — a small but real cash-flow edge, especially combined with zero-MDR QRIS for website channels since October 2026. If you haven't recalculated per-channel margins since these changes landed, start with our marketplace vs website net margin breakdown.
4. Data Model: Adding PPh 22 Fields to Your Sales Records
For the withholding to be reconcilable, it must be a first-class field in your sales records — not a mental note taken when a payout looks slightly off. Add tax columns to the order record:
order:
  order_id: "ORD-2026-10-00042"
  channel: "marketplace"            # marketplace | website | whatsapp
  marketplace_entity: "PT Tokopedia"
  transaction_date: "2026-10-14"
  settlement_date: "2026-10-18"
  gross_amount: 1200000             # gross turnover after seller-funded marketing
  ppn_amount: 0                     # fill in if you are VAT-registered
  pph22_withheld: 6000              # 0.5% x gross_amount, from the payout breakdown
  pph22_bukti_potong: "BP-TPD-202610-0117"
  admin_fee: 24000                  # platform fee, kept separate from tax
  payout_net: 1170000
Three practical rules when exporting from each platform's dashboard:
- Pull the payout breakdown (turnover, fees, PPh 22) per settlement, not just the net figure. All major platforms expose it in their sales reports.
- Store the withholding slip reference (
bukti potong) on the order record. Without it, year-end reconciliation turns into detective work. - Keep
admin_feeseparate frompph22_withheld. Merging the two makes your margin look worse and makes a statutory tax look like an avoidable fee.
If your sales records still live in a spreadsheet, our guide on website sales data for Coretax annual filing covers the monthly structure that aligns with DJP reporting — the PPh 22 fields above just bolt onto it.
5. Automating the Rp500 Million Threshold
The most expensive mistake under this policy is not the rate — it is missing the statement deadline when turnover jumps past Rp500 million mid-year. The classic scenario: a big campaign month pushes your year-to-date turnover from Rp420 million to Rp610 million. The "exceeding Rp500 million" statement must reach the marketplaces by the end of that month.
Build one simple query over your sales records:
-- Year-to-date turnover across channels, one NPWP
SELECT SUM(gross_amount) AS ytd_turnover
FROM orders
WHERE transaction_date >= '2026-01-01'
  AND status = 'paid';
Then set two notification thresholds:
- Rp450 million (90%): internal warning — prepare the "exceeding" statement and confirm your NPWP/NIK and correspondence address are still valid.
- Rp500 million (100%): alarm — deliver the statement to every marketplace no later than the end of this month.
If you run multiple shops under different NPWPs (separate NPWPs are counted separately), make sure the query groups by NPWP. An automation this small saves you penalty interest and end-of-month drama.
6. Reconciling Withholding Slips into the Annual Coretax Return
Every month, download the PPh 22 withholding slip (bukti pemotongan/pemungutan) from each marketplace — usually available in the tax or seller-reports menu. The year-to-date total withheld across all platforms is the number you will eventually rely on:
- As a tax credit within the running year, or
- As part of the 0.5% final income tax settlement for individuals using the final scheme (PP 55/2022 as amended by PP 20/2026).
The monthly reconciliation routine we run for clients:
- Sum the
pph22_withheldcolumn per month from your database. - Match it against the total slips issued by each marketplace. Small gaps usually come from settlements that straddle a month boundary.
- Record the final income tax you pay yourself for the website channel through Coretax — never double-count it against the marketplace withholding.
That way, when the annual return season arrives in Coretax, your credit figures are clean and there is no guesswork. For the other obligations that come with marketplace selling, see also our guide to PPN 11% and Coretax for business websites.
Conclusion
The marketplace PPh 22 withholding at 0.5% since October 1, 2026 is not a crisis — it is an existing obligation whose mechanics just got centralized. What determines the outcome for your business is discipline on three things: submit the Rp500 million turnover statement if you qualify, monitor the threshold automatically, and treat the withholding as a data field reconciled against monthly slips. The own-website channel offers cleaner cash timing and administration — worth weighing as you plan your 2027 channel strategy.
If you want this withholding tracked automatically in your sales system, start with a small data model like the one above — Start a conversation with us at Zero Args Technology.
Frequently asked questions
Is the marketplace PPh 22 withholding a new tax?
No. It is a collection mechanism for an existing income tax obligation, set at 0.5% of gross turnover, and can be credited against your annual tax or counted toward final income tax settlement.
How do I submit the Rp500 million turnover statement?
Prepare the letter using the format in Indonesia's PMK 37/2025 regulation, sign it over an IDR 10,000 duty stamp, and upload it through each marketplace's designated feature. One statement per NPWP/NIK covers all accounts and all marketplaces.
Does my own website's sales also get withheld?
No third party withholds it, because your own website is not a marketplace appointed by Indonesia's tax office (DJP). You still pay the 0.5% final income tax yourself each month through Coretax, so the cash timing differs from marketplace channels.
When does collection start after turnover passes Rp500 million?
Submit the stamped statement marked as exceeding Rp500 million no later than the end of the month the threshold is passed, and marketplaces begin withholding 0.5% the following month.